INDUSTRY SERIES: FINANCIAL MANAGEMENT FOR WHOLESALE DISTRIBUTION COMPANIES
This is Part 6 of our ongoing industry series on financial management. Previous posts covered PR and advertising agencies, law firms, IT and technology companies, architecture and engineering firms, and accounting firms. Each post focuses on the financial management challenges, metrics, and oversight practices specific to one industry.
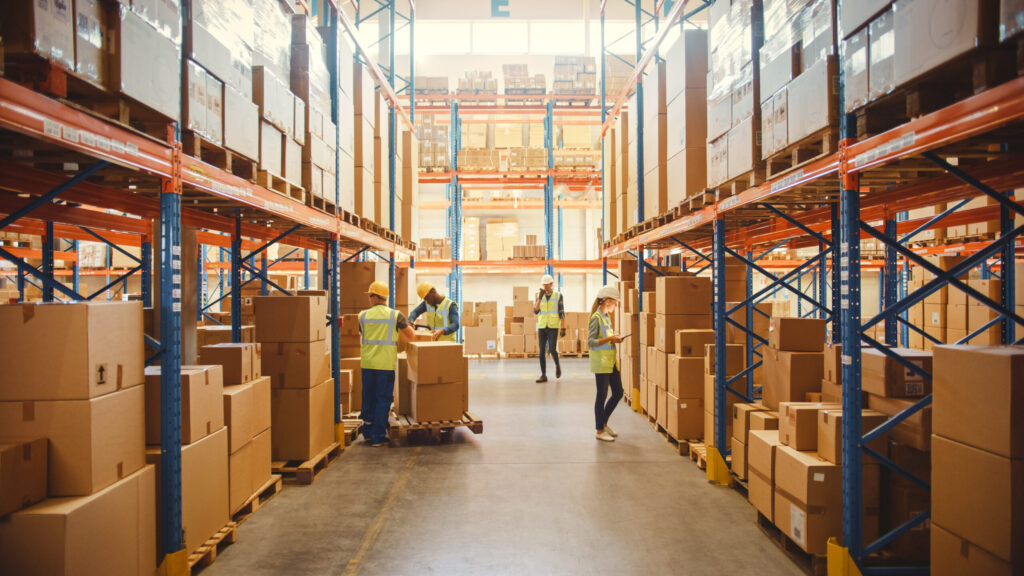
Early in my career I was taught that if you really want to understand an inventory-based business, you need to walk the warehouse. Not just review the reports — walk the floor.
Most business owners are surprised when I ask to do that. They expect a CFO to want to sit down with the financials. And we will get there. But the way product is organized on the shelves, the stocking and picking procedures, the shelving methodology, the movement of the forklifts and pallet jacks — all of it tells you something about how well a business actually operates before a single number is discussed. The warehouse does not lie.
What follows is what I look for once we get to the numbers.
Inventory Is Your Biggest Asset and Your Biggest Risk
In wholesale distribution, inventory is not just a line on the balance sheet. It is the business. How you buy it, how you price it, how long you hold it, and how well it moves off the shelf determines whether the business is profitable or just busy.
One of the most important metrics here is Days Inventory Outstanding, or DIO. DIO tells you how long, on average, your inventory sits before it is sold. A high DIO means capital is tied up in product that is not moving. A low DIO means you are turning inventory efficiently and freeing up cash.
Most distribution businesses know their DIO. Far fewer are asking the harder question: which products are driving it up, and why?
Not All Slow-Moving Inventory Is a Problem — But All of It Needs a Decision Behind It
Here is something that does not get said enough: long-sitting inventory is not automatically bad management. Context matters.
I worked with a precision machine parts company that carried a significant amount of inventory that had been on the shelves for years. When I asked the CFO about it, he smiled. He knew exactly what I was getting at. His answer was honest and well-reasoned: there was no debt or accounts payable floating behind that inventory. The parts were highly specialized and difficult to source. And because of that scarcity, the expected profit margin on those items was high enough that carrying them for years was a deliberate and defensible business decision.
That is good inventory management. The inventory was slow. The decision behind it was sound.
The problem is not slow-moving inventory. The problem is slow-moving inventory with no decision behind it. Every item sitting on your shelves for an extended period should have an answer to the question: why is this here, and do we still want it here? If the answer is a shrug, that is the problem worth solving.
Seasonal Inventory Is Where the Real Risk Hides
Seasonal products carry a risk that general inventory does not. If the purchasing decision is wrong, you are not just sitting on slow-moving product for a few weeks. You may be sitting on it for an entire year.
Summer sandals are not a hot item in November. Outdoor furniture does not move in February. Holiday packaging has a window measured in weeks. If you overbuy on a seasonal item and miss the selling season, that inventory is not just slow. It is frozen. It is sitting on your shelves, consuming warehouse space, tying up capital that could be redeployed, and waiting for next year’s season to come around before it has any real chance of moving.
That is a twelve-month capital commitment on a purchasing decision that may have taken ten minutes.
The financial impact compounds quickly. The capital tied up in unsold seasonal inventory is capital you cannot use to purchase next season’s product. If your credit line is supporting inventory purchases, you are paying interest on product that is generating zero revenue. And if next year’s version of the same product arrives before this year’s sells through, you now have two seasons of inventory competing for the same shelf space and the same buyer.
The right response is not to stop carrying seasonal items. It is to put real financial analysis behind the purchasing decision before it is made. That means reviewing prior year sell-through rates by SKU, understanding your carrying cost per unit per month, modeling the downside scenario if the season underperforms, and setting a clear liquidation threshold so you know when to mark down and move on rather than hold and hope.
The Cash Flow Gap Between Buying and Selling
Wholesale distribution businesses often face a structural cash flow challenge that has nothing to do with profitability. You have to pay your vendors before your customers pay you, and the gap between those two dates is where cash disappears.
If you are paying vendors in 30 days and collecting from customers in 60, you are effectively financing your customers’ businesses with your own capital. Multiply that gap across your full inventory position and the cash flow impact becomes significant.
Managing this gap requires attention to both sides. On the vendor side, negotiate payment terms as aggressively as the relationship allows. On the customer side, enforce collection terms, monitor your Days Sales Outstanding closely, and flag slow payers before they become a cash flow problem.
Freight and Logistics Costs Deserve Their Own Analysis
Freight is often treated as a cost of doing business rather than a cost that can be managed. That is a missed opportunity.
Freight and logistics costs vary significantly by order size, shipping lane, carrier, and timing. Distribution businesses that analyze their freight costs at the product and customer level frequently discover that certain orders, certain customers, or certain shipping patterns are significantly less profitable than they appear on the surface. The margin looks fine until freight is allocated correctly.
Margin by Product Line Is Not Optional
Gross margin at the company level tells you whether the business is generally healthy. Margin by product line tells you which products are actually making money and which ones are subsidized by the rest of the catalog.
In distribution, it is common to find that a significant portion of SKUs are generating thin or negative contribution margins once carrying costs, freight, and handling are fully allocated. Owners are often surprised by this analysis. The product sells. The revenue shows up. But the net contribution after all costs is not what they assumed.
Running margin analysis by product line, by customer, and by category on a regular basis is one of the highest-value financial exercises a distribution business can do. It informs pricing decisions, purchasing decisions, and the harder conversation about which products belong in the catalog at all.
The Questions Worth Asking
Before the next purchasing cycle, before the next seasonal buy, before the next vendor negotiation, these are the questions your financial team should be able to answer:
What is our current DIO, and which product categories are driving it?
For each item that has been sitting for an extended period, what is the decision behind it? Is that decision still sound?
For each seasonal item we are planning to purchase, what happens to our cash position if we sell through 60% instead of 100%?
What is our actual cash conversion cycle from vendor payment to customer collection, and how does that compare to our available credit?
Are we analyzing freight and logistics costs at the product and customer level, or only in aggregate?
When did we last run a full margin analysis by product line, and do we know which SKUs are not pulling their weight?
The Bottom Line
Wholesale distribution is a cash-intensive business where the difference between a profitable operation and a struggling one often comes down to purchasing discipline, inventory management, and an honest look at the numbers behind every product in the catalog.
If your financial team is not providing that level of analysis on a regular basis, that is the gap worth closing.
Ready to Elevate Your Financial Strategy?
Whether you need fractional CFO leadership or outsourced accounting support, we're here to help your business ascend.
Schedule a Conversation